Q2 2026 housing starts weakened nationally as regional markets diverged
National overview
Housing starts weakened through the second quarter, with the year-over-year decline becoming more pronounced as the period progressed.
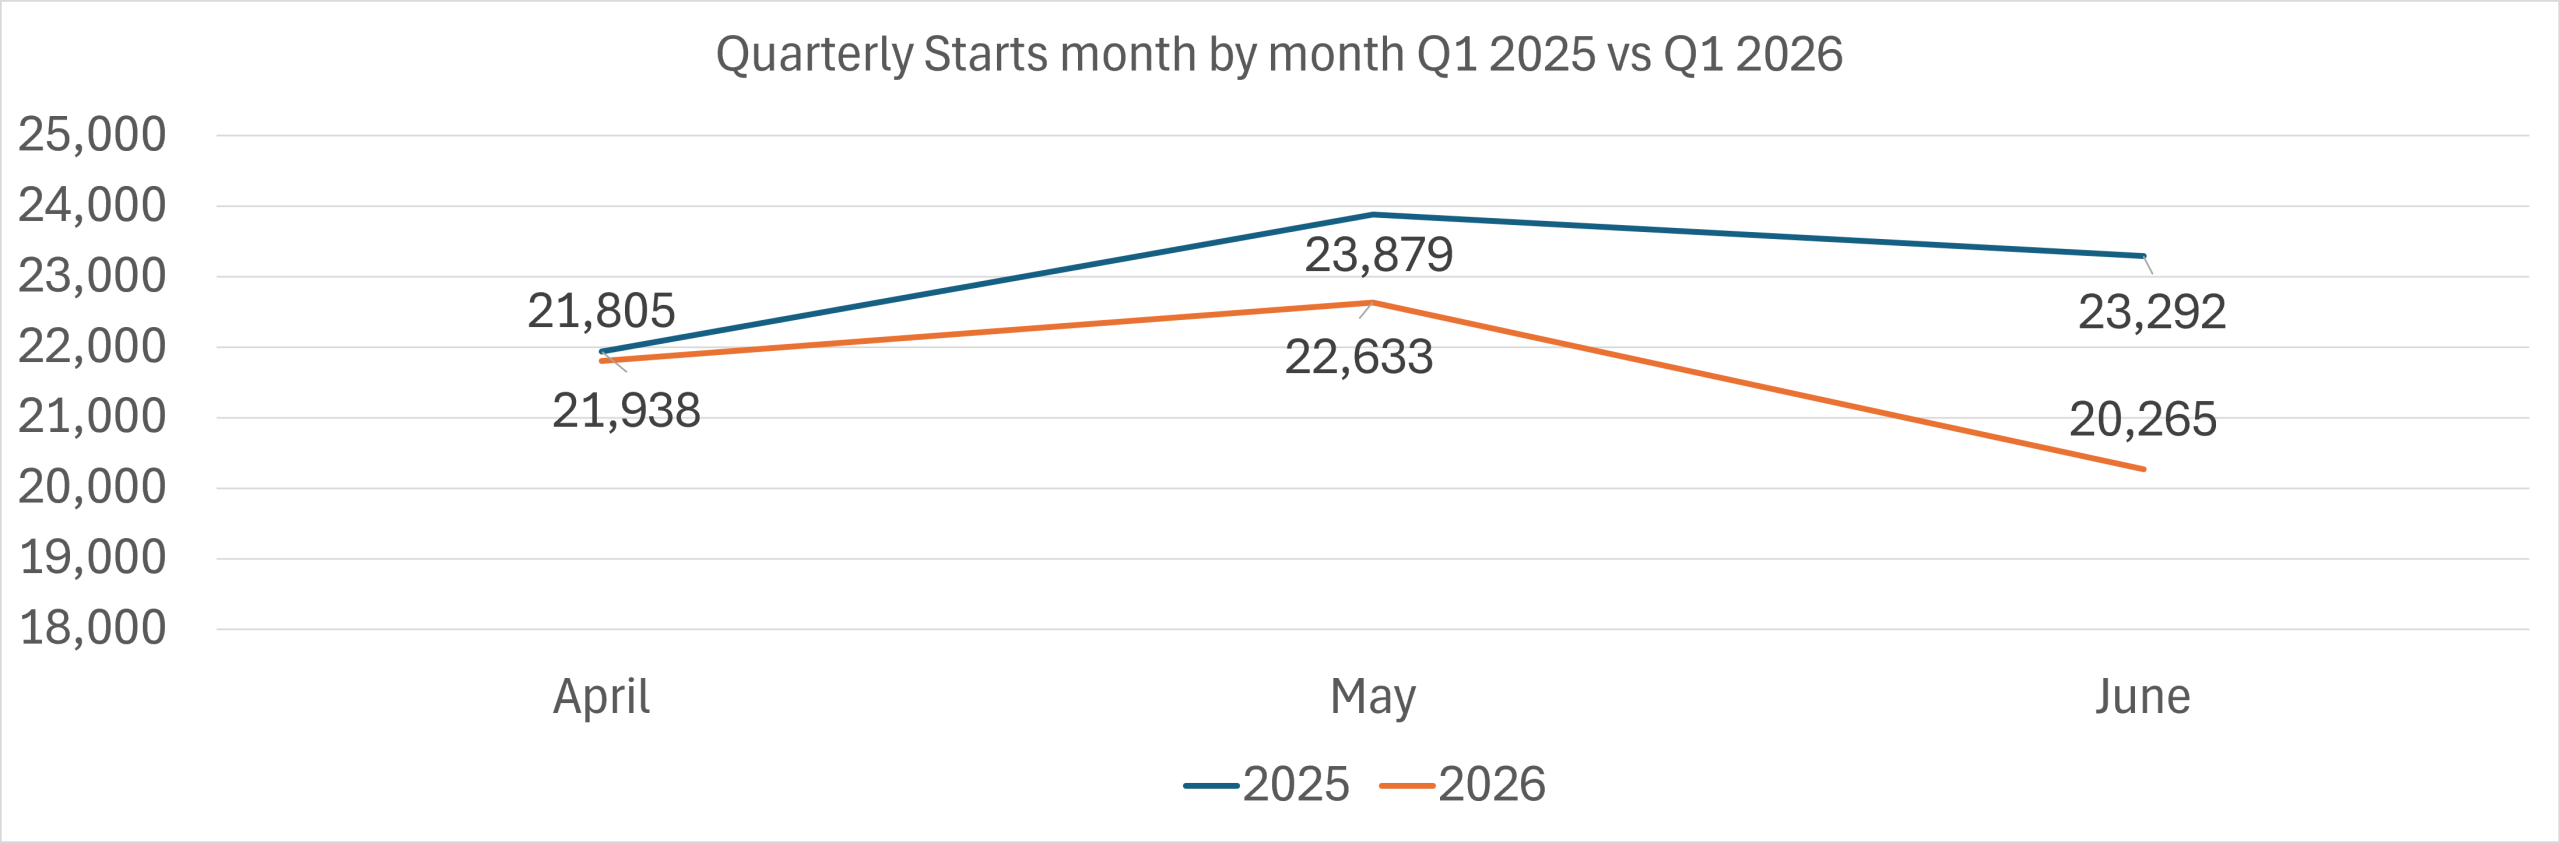
April starts came in at 21,805, only 0.6% below the 21,938 recorded a year earlier. In May, starts fell 5.2%, from 23,879 to 22,633. By June, the decline had widened to 13.0%, with starts dropping from 23,292 to 20,265.
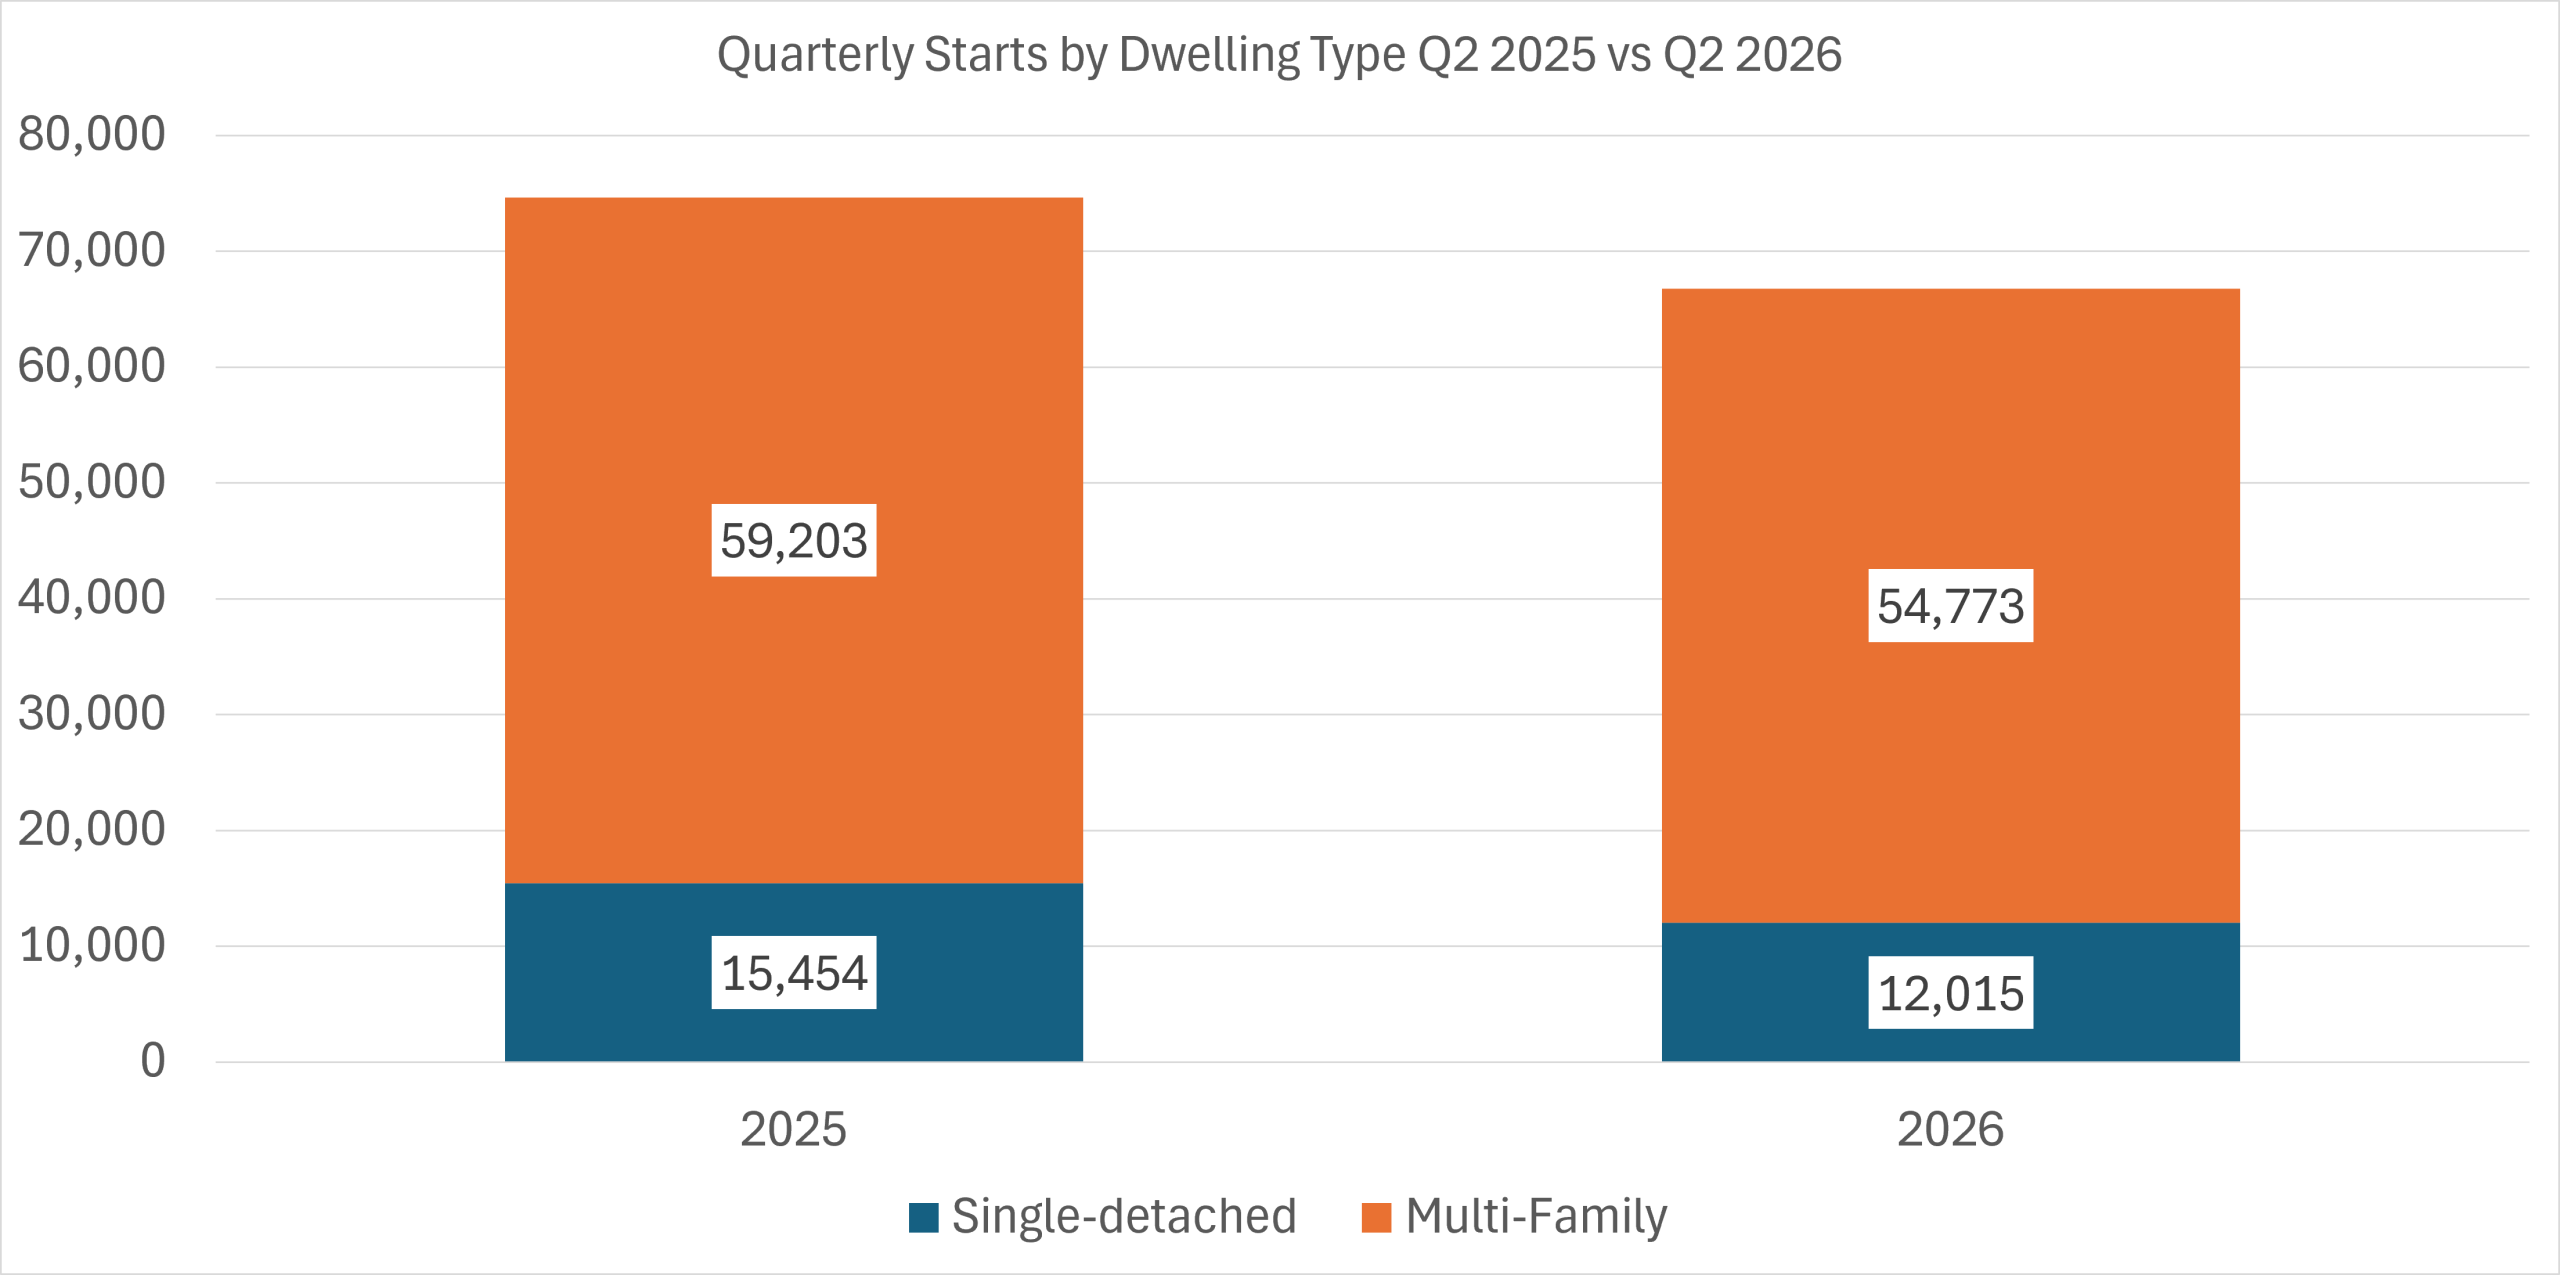
The dwelling mix shows where much of that weakness was concentrated. Single-detached starts fell from 15,454 in Q2 2025 to 12,015 in Q2 2026, a decline of 22.3%. Multi-family starts decreased from 59,203 to 54,773, down 7.5%.
Multi-family construction continued to account for the large majority of units started during the quarter, but its lower volume still represented 4,430 fewer starts than a year earlier. Single-detached starts declined by 3,439 units despite beginning from a much smaller base.
On the dwelling-type measure, total starts fell from 74,657 to 66,788, a year-over-year decline of approximately 10.5%. The figures point to a quarter in which overall activity weakened and the contraction was considerably sharper in single-detached construction than in multi-family development.
 Provincial and CMA overview
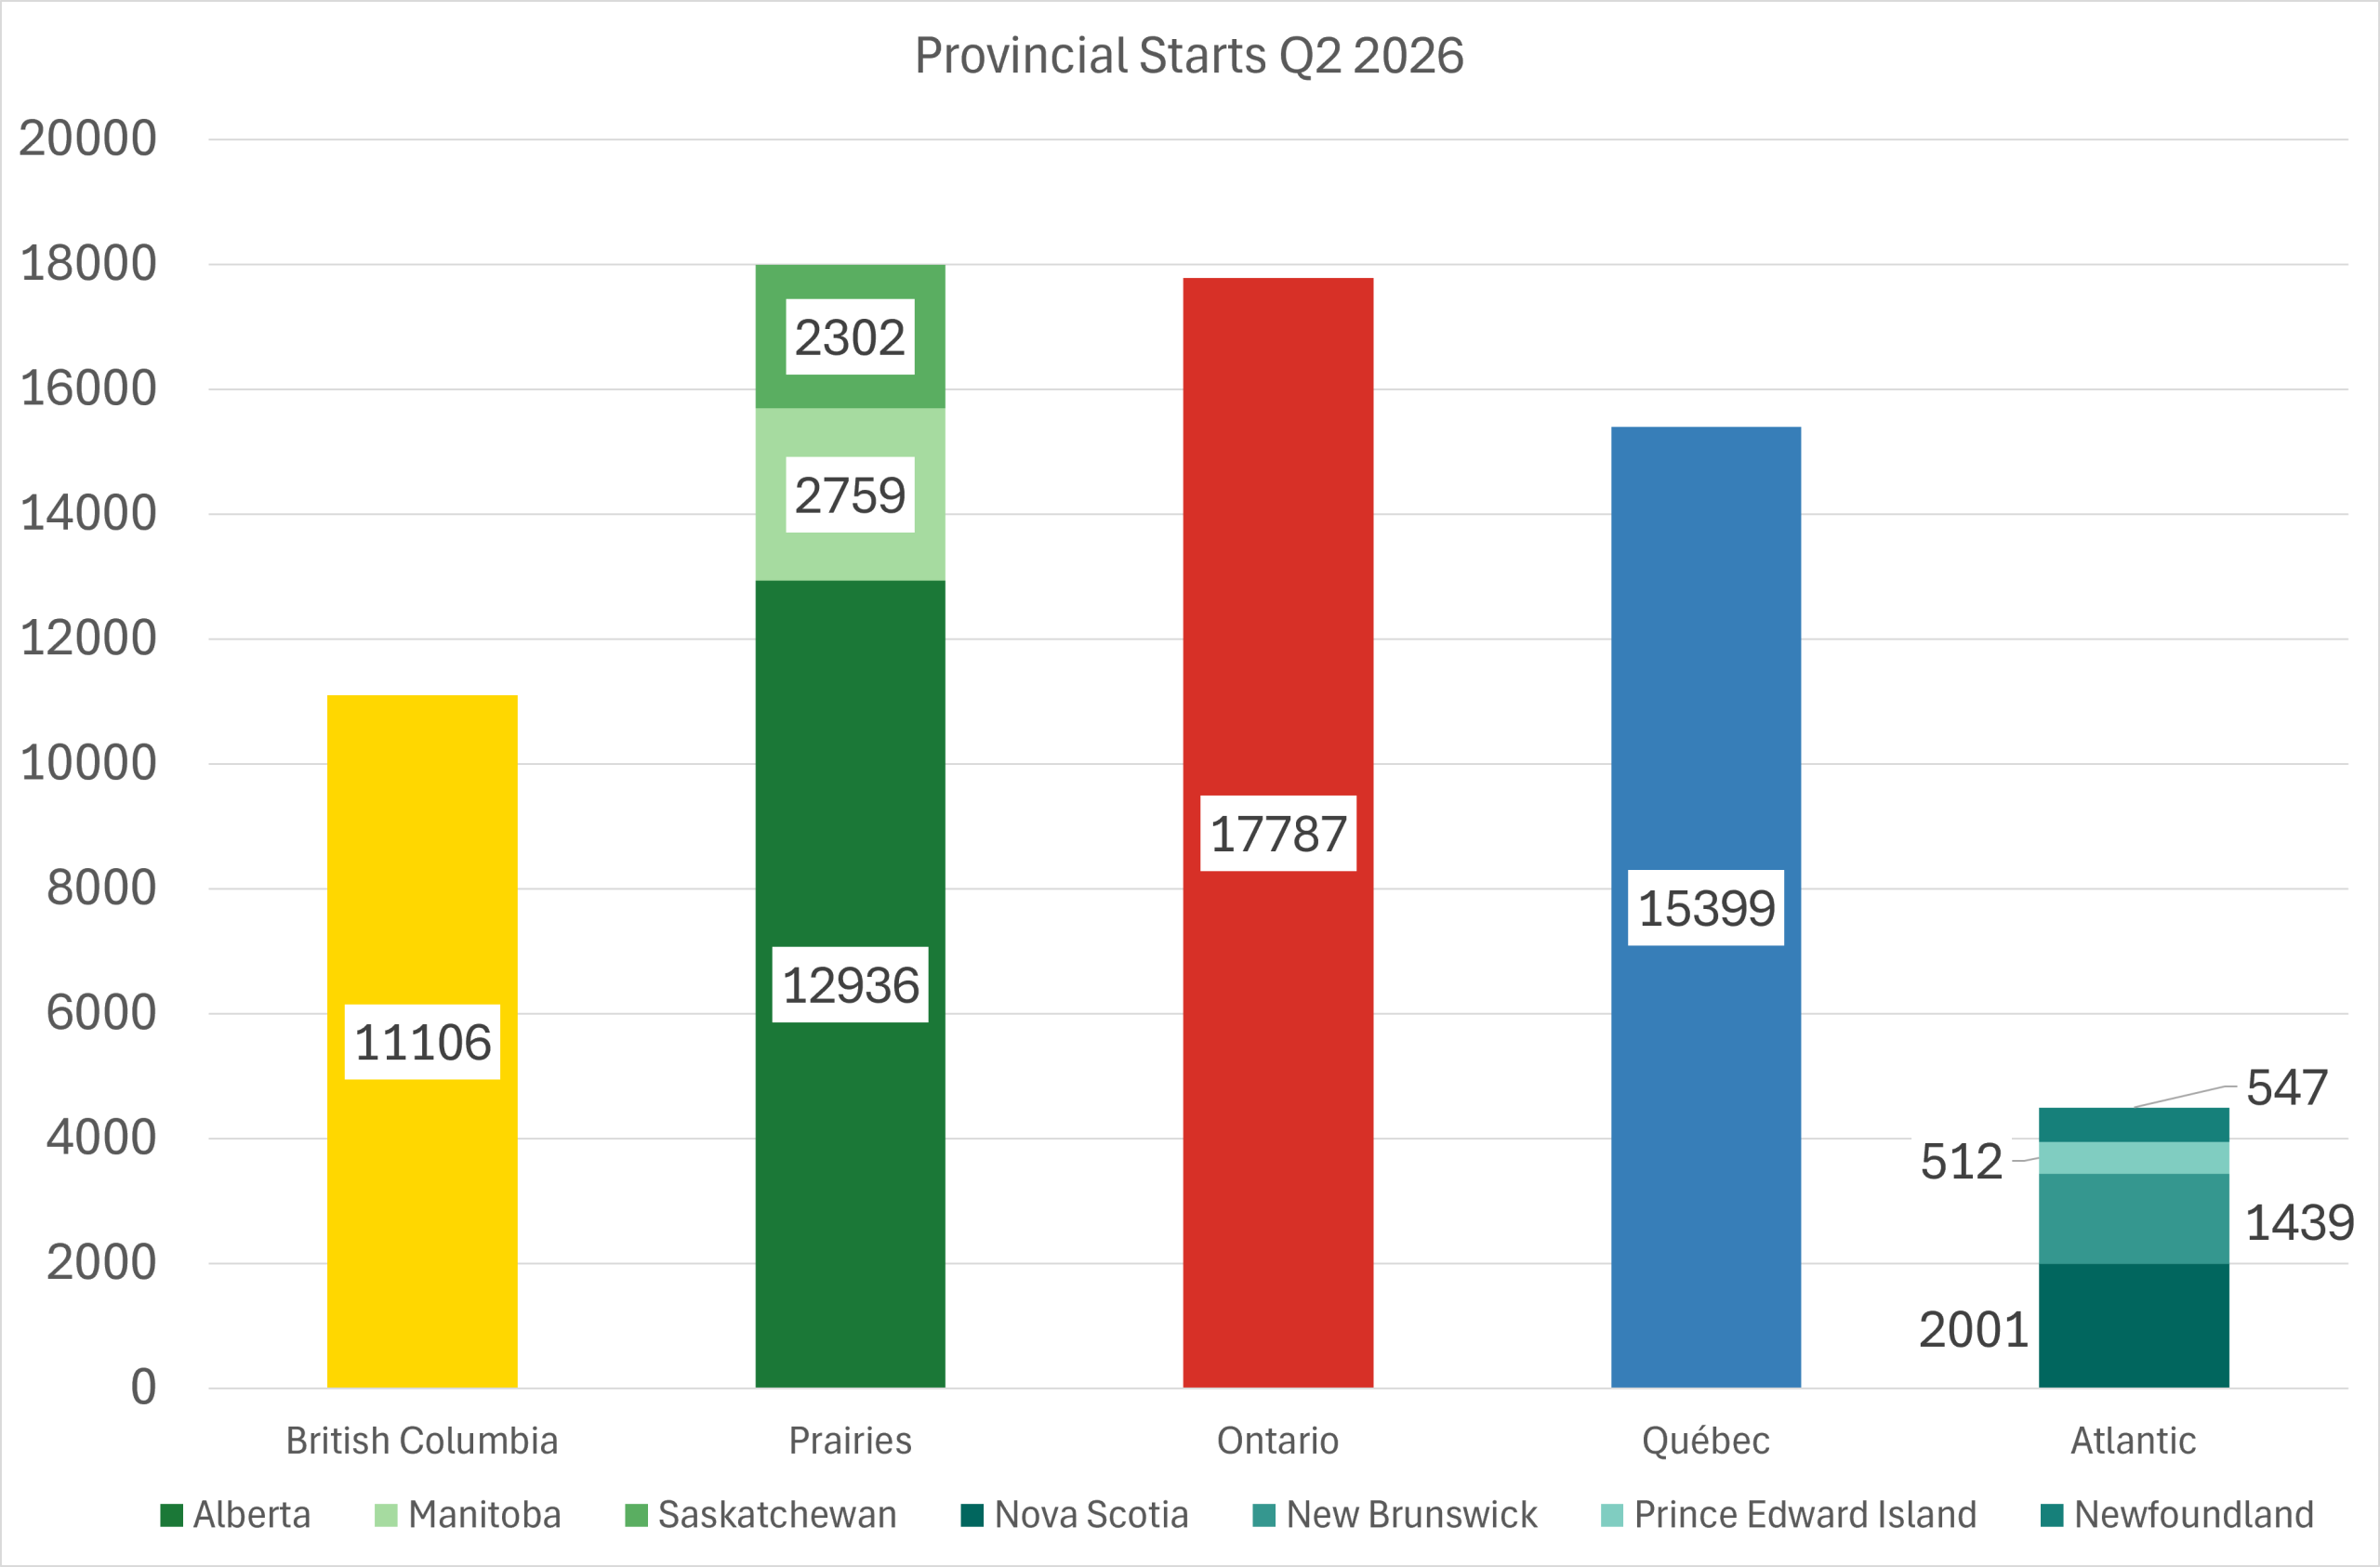
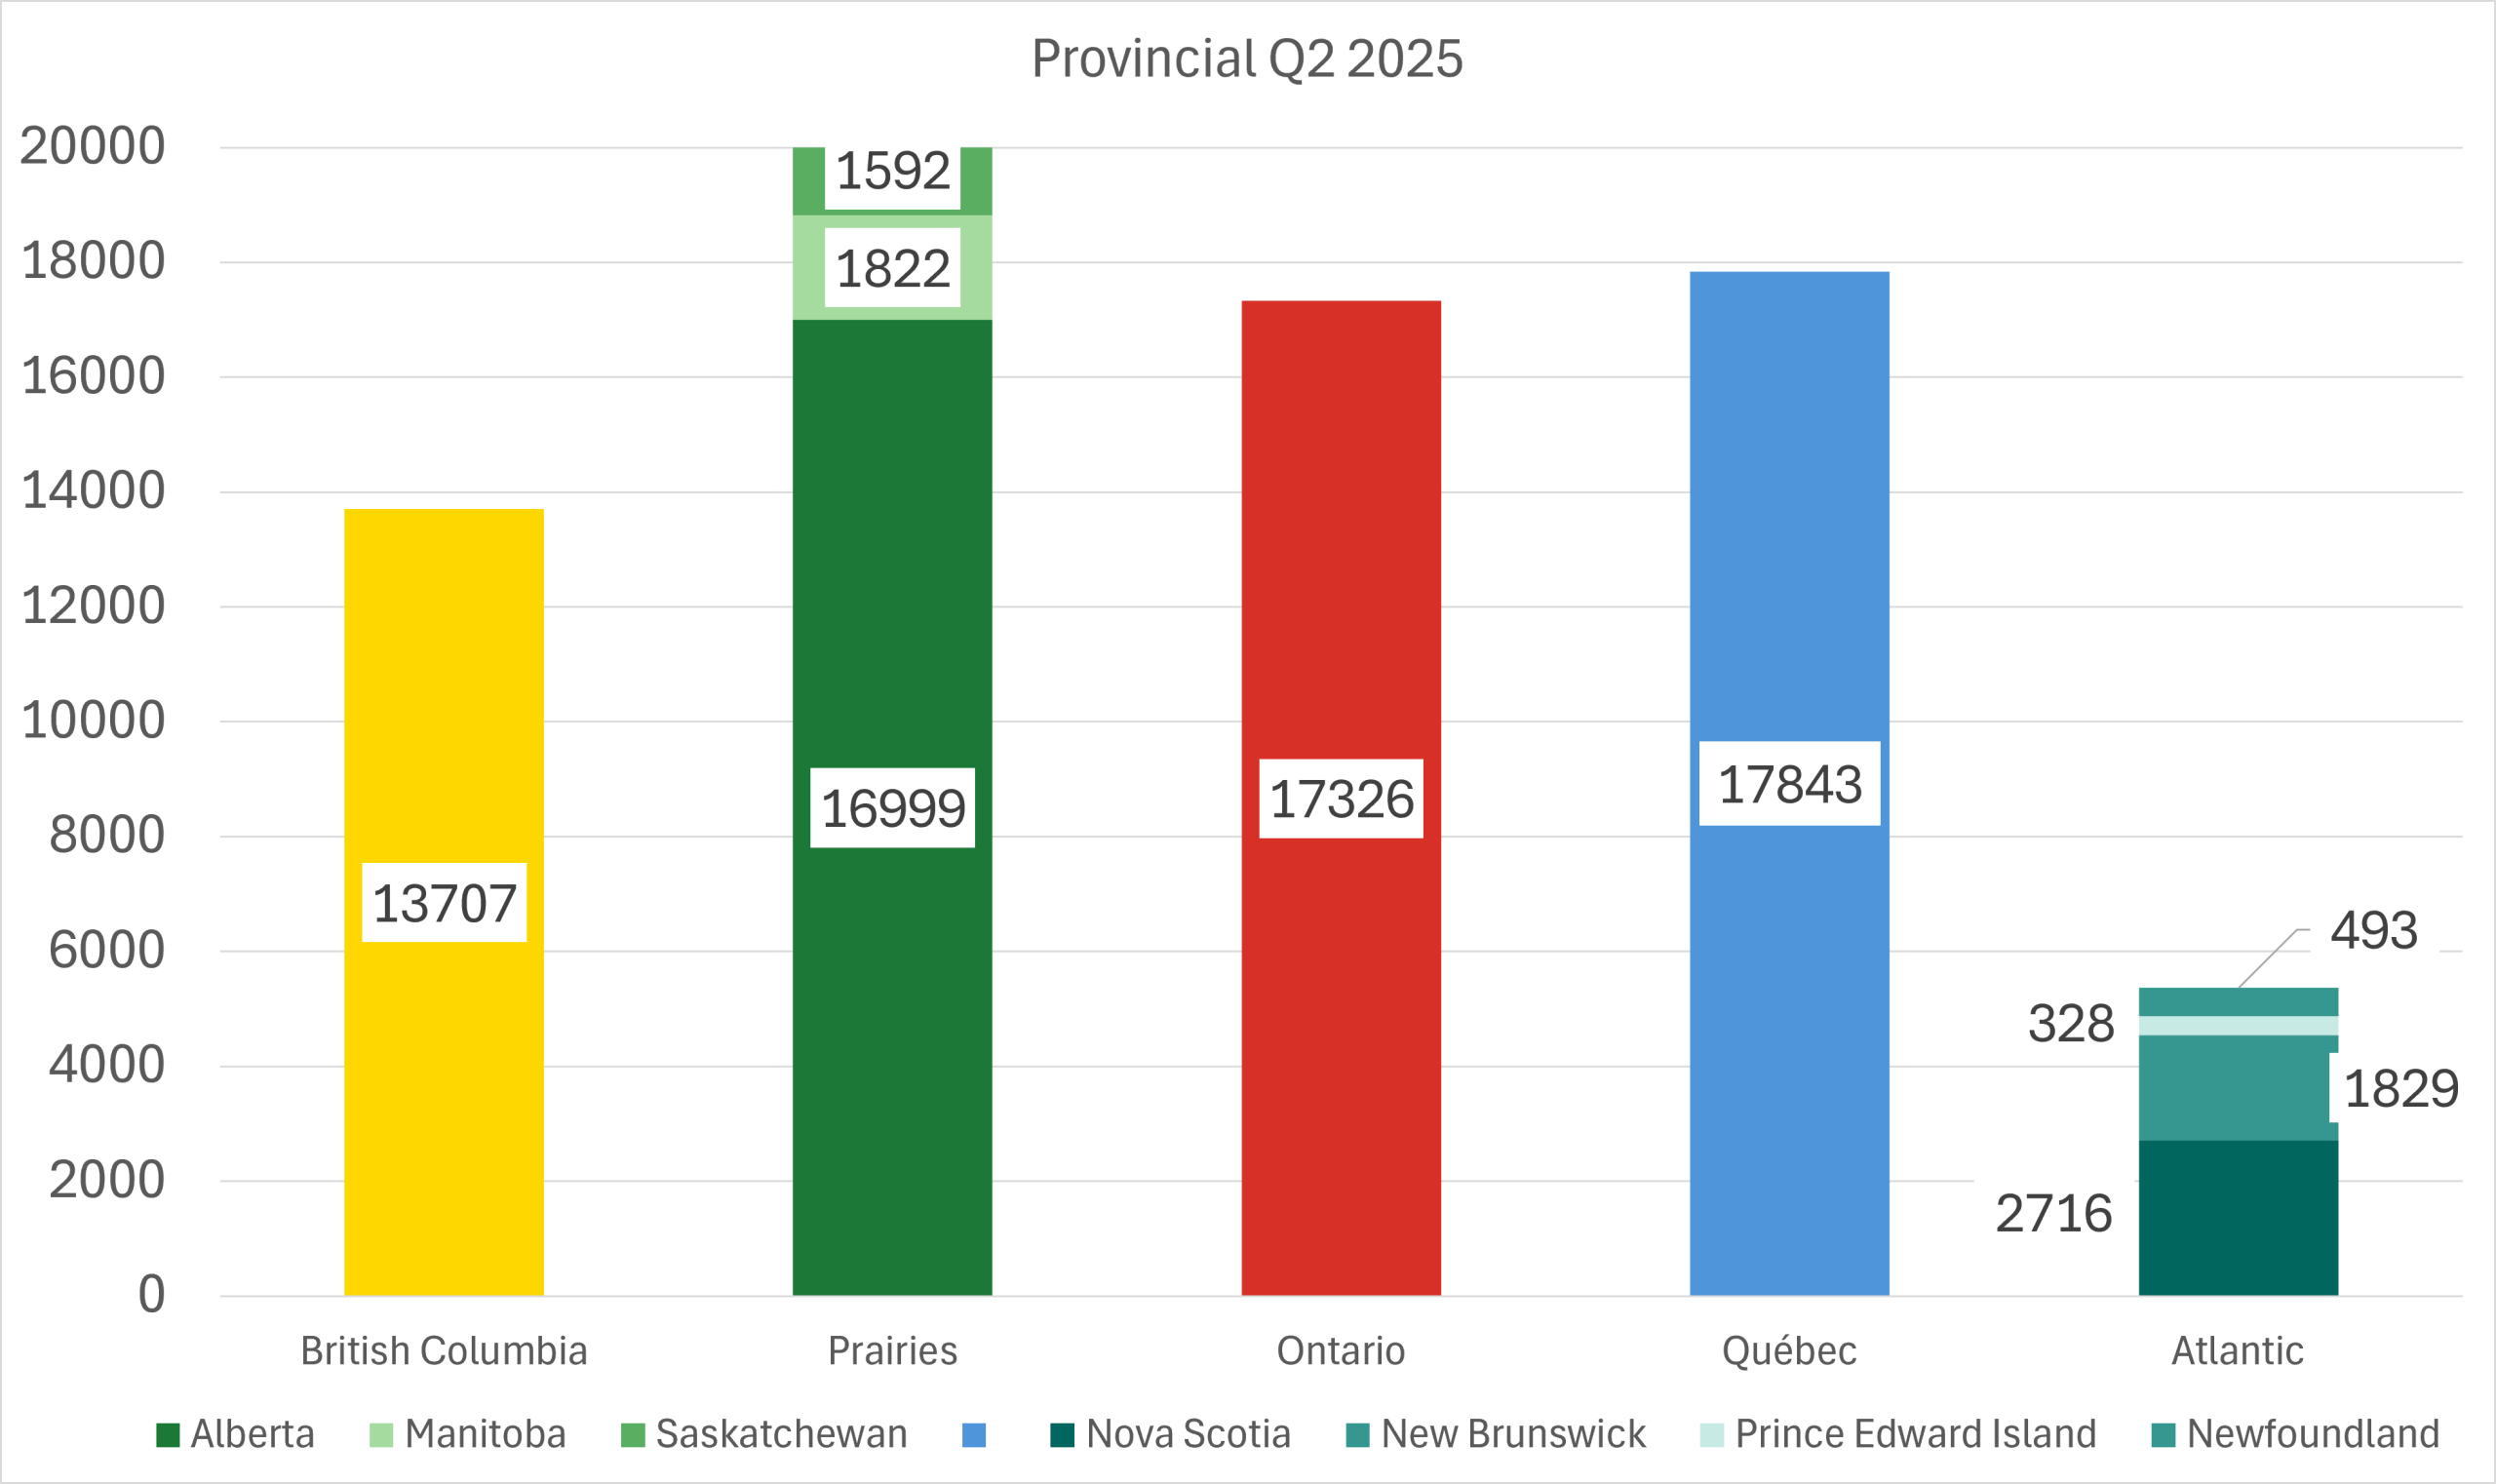
The national decline was not evenly distributed. British Columbia, Alberta and Quebec recorded sizable reductions in starts, while Ontario was slightly higher and Manitoba and Saskatchewan posted substantial gains. Atlantic Canada was mixed.
British Columbia
British Columbia starts fell 19.0%, from 13,707 in Q2 2025 to 11,106 this year. Lower activity in Vancouver, Victoria and Kelowna outweighed strong increases in several smaller markets.
- Vancouver: 7,937 → 5,815 (-26.7%)
- Victoria: 1,727 → 1,180 (-31.7%)
- Kelowna: 1,273 → 584 (-54.1%)
- Abbotsford-Mission: 590 → 700 (+18.6%)
- Chilliwack: 175 → 420 (+140.0%)
- Nanaimo: 103 → 375 (+264.1%)
- Kamloops: 41 → 526 (+1,182.9%)
Kamloops recorded the largest percentage increase, although the comparison starts from only 41 units in Q2 2025.
Alberta
Alberta recorded the largest decline among the three biggest provincial markets, with starts falling 23.9% from 16,999 to 12,936. Weakness extended across the CMAs reported.
- Calgary: 8,441 → 6,346 (-24.8%)
- Edmonton: 6,773 → 5,283 (-22.0%)
- Red Deer: 238 → 86 (-63.9%)
- Lethbridge: 179 → 158 (-11.7%)
The declines in Calgary and Edmonton accounted for much of the provincial reduction, with both markets down by more than 20%.
Manitoba and Saskatchewan
The other Prairie provinces moved in the opposite direction. Manitoba starts increased 51.4%, from 1,822 to 2,759, while Saskatchewan rose 44.6%, from 1,592 to 2,302.
- Winnipeg: 1,452 → 2,285 (+57.4%)
- Regina: 428 → 771 (+80.1%)
- Saskatoon: 1,020 → 1,272 (+24.7%)
Growth was therefore visible in the principal CMAs of both provinces rather than being confined to smaller centres.
Ontario
Ontario starts increased 2.7%, from 17,326 to 17,787. That relatively modest provincial change concealed large movements between individual CMAs.
- Toronto: 7,503 → 8,336 (+11.1%)
- Kitchener-Cambridge-Waterloo: 372 → 1,208 (+224.7%)
- London: 485 → 1,471 (+203.3%)
- Windsor: 292 → 393 (+34.6%)
- Barrie: 150 → 245 (+63.3%)
- Belleville-Quinte West: 66 → 115 (+74.2%)
- Thunder Bay: 43 → 130 (+202.3%)
- Peterborough: 11 → 20 (+81.8%)
- Brantford: 865 → 295 (-65.9%)
- Kingston: 589 → 244 (-58.6%)
- Hamilton: 405 → 237 (-41.5%)
- Guelph: 41 → 32 (-22.0%)
- Oshawa: 231 → 202 (-12.6%)
- St. Catharines-Niagara: 534 → 534 (0.0%)
Toronto provided growth from the province’s largest market, while Kitchener-Cambridge-Waterloo and London posted particularly large increases. Those gains were partly offset by sharp reductions in Brantford, Kingston and Hamilton.
Quebec
Quebec starts fell 13.7%, from 17,843 to 15,399. Montreal moved against that provincial decline, while several other CMAs recorded lower activity.
- Montréal: 7,365 → 8,537 (+15.9%)
- Québec: 3,321 → 2,490 (-25.0%)
- Trois-Rivières: 531 → 355 (-33.1%)
- Sherbrooke: 557 → 438 (-21.4%)
- Drummondville: 358 → 389 (+8.7%)
- Saguenay: 154 → 286 (+85.7%)
The increase in Montreal was not enough to offset declines in Quebec City, Trois-Rivières and Sherbrooke.
Atlantic Canada
Results were divided across Atlantic Canada. Nova Scotia starts declined 26.3%, from 2,716 to 2,001, while New Brunswick fell 21.3%, from 1,829 to 1,439. Prince Edward Island increased from 328 to 512 starts, and Newfoundland and Labrador rose from 493 to 547.
- Halifax: 1,960 → 1,289 (-34.2%)
- Moncton: 765 → 601 (-21.4%)
- Saint John: 150 → 83 (-44.7%)
- Fredericton: 344 → 344 (0.0%)
- St. John’s: 306 → 432 (+41.2%)
Halifax, Moncton and Saint John followed the declines recorded in Nova Scotia and New Brunswick, while St. John’s moved higher alongside the increase in Newfoundland and Labrador.
Overall, Q2 housing starts were characterized by a weaker national trajectory but sharply different regional outcomes. Large markets including Calgary, Edmonton, Vancouver and Halifax recorded substantial declines, while Toronto, Winnipeg and several Ontario and Saskatchewan CMAs moved higher. The spread between those markets makes the provincial and metropolitan picture more useful than the national total alone in assessing where construction activity was gaining or losing ground.
 Tyler Holt is the Editor of Wood Industry / Le monde du bois magazine. He has a master’s degree in literature and publication, and years of experience in the publishing and digital media industry. His main area of study is the effect of digital technologies on industrial and networked production.