Q1 2025 Housing Starts: Regional Growth Offsets Urban Slowdowns
National Snapshot
Early‑2025 housing data tell a story of contrasts rather than competition. According to the Canada Mortgage and Housing Corporation (CMHC), 45,302 new homes began construction in Q1 2025 across centres of 10 000 people or more—an 8.6 percent dip from the same period last year. Yet that headline masks pockets of strong expansion. Several provinces recorded substantial gains, particularly in multi‑unit rental projects, while some of Canada’s largest metropolitan areas experienced a pause after an unusually active 2023. For secondary wood manufacturers, the takeaway is not who is “winning” or “losing,” but where momentum is shifting and how to align supply chains with evolving regional demand.
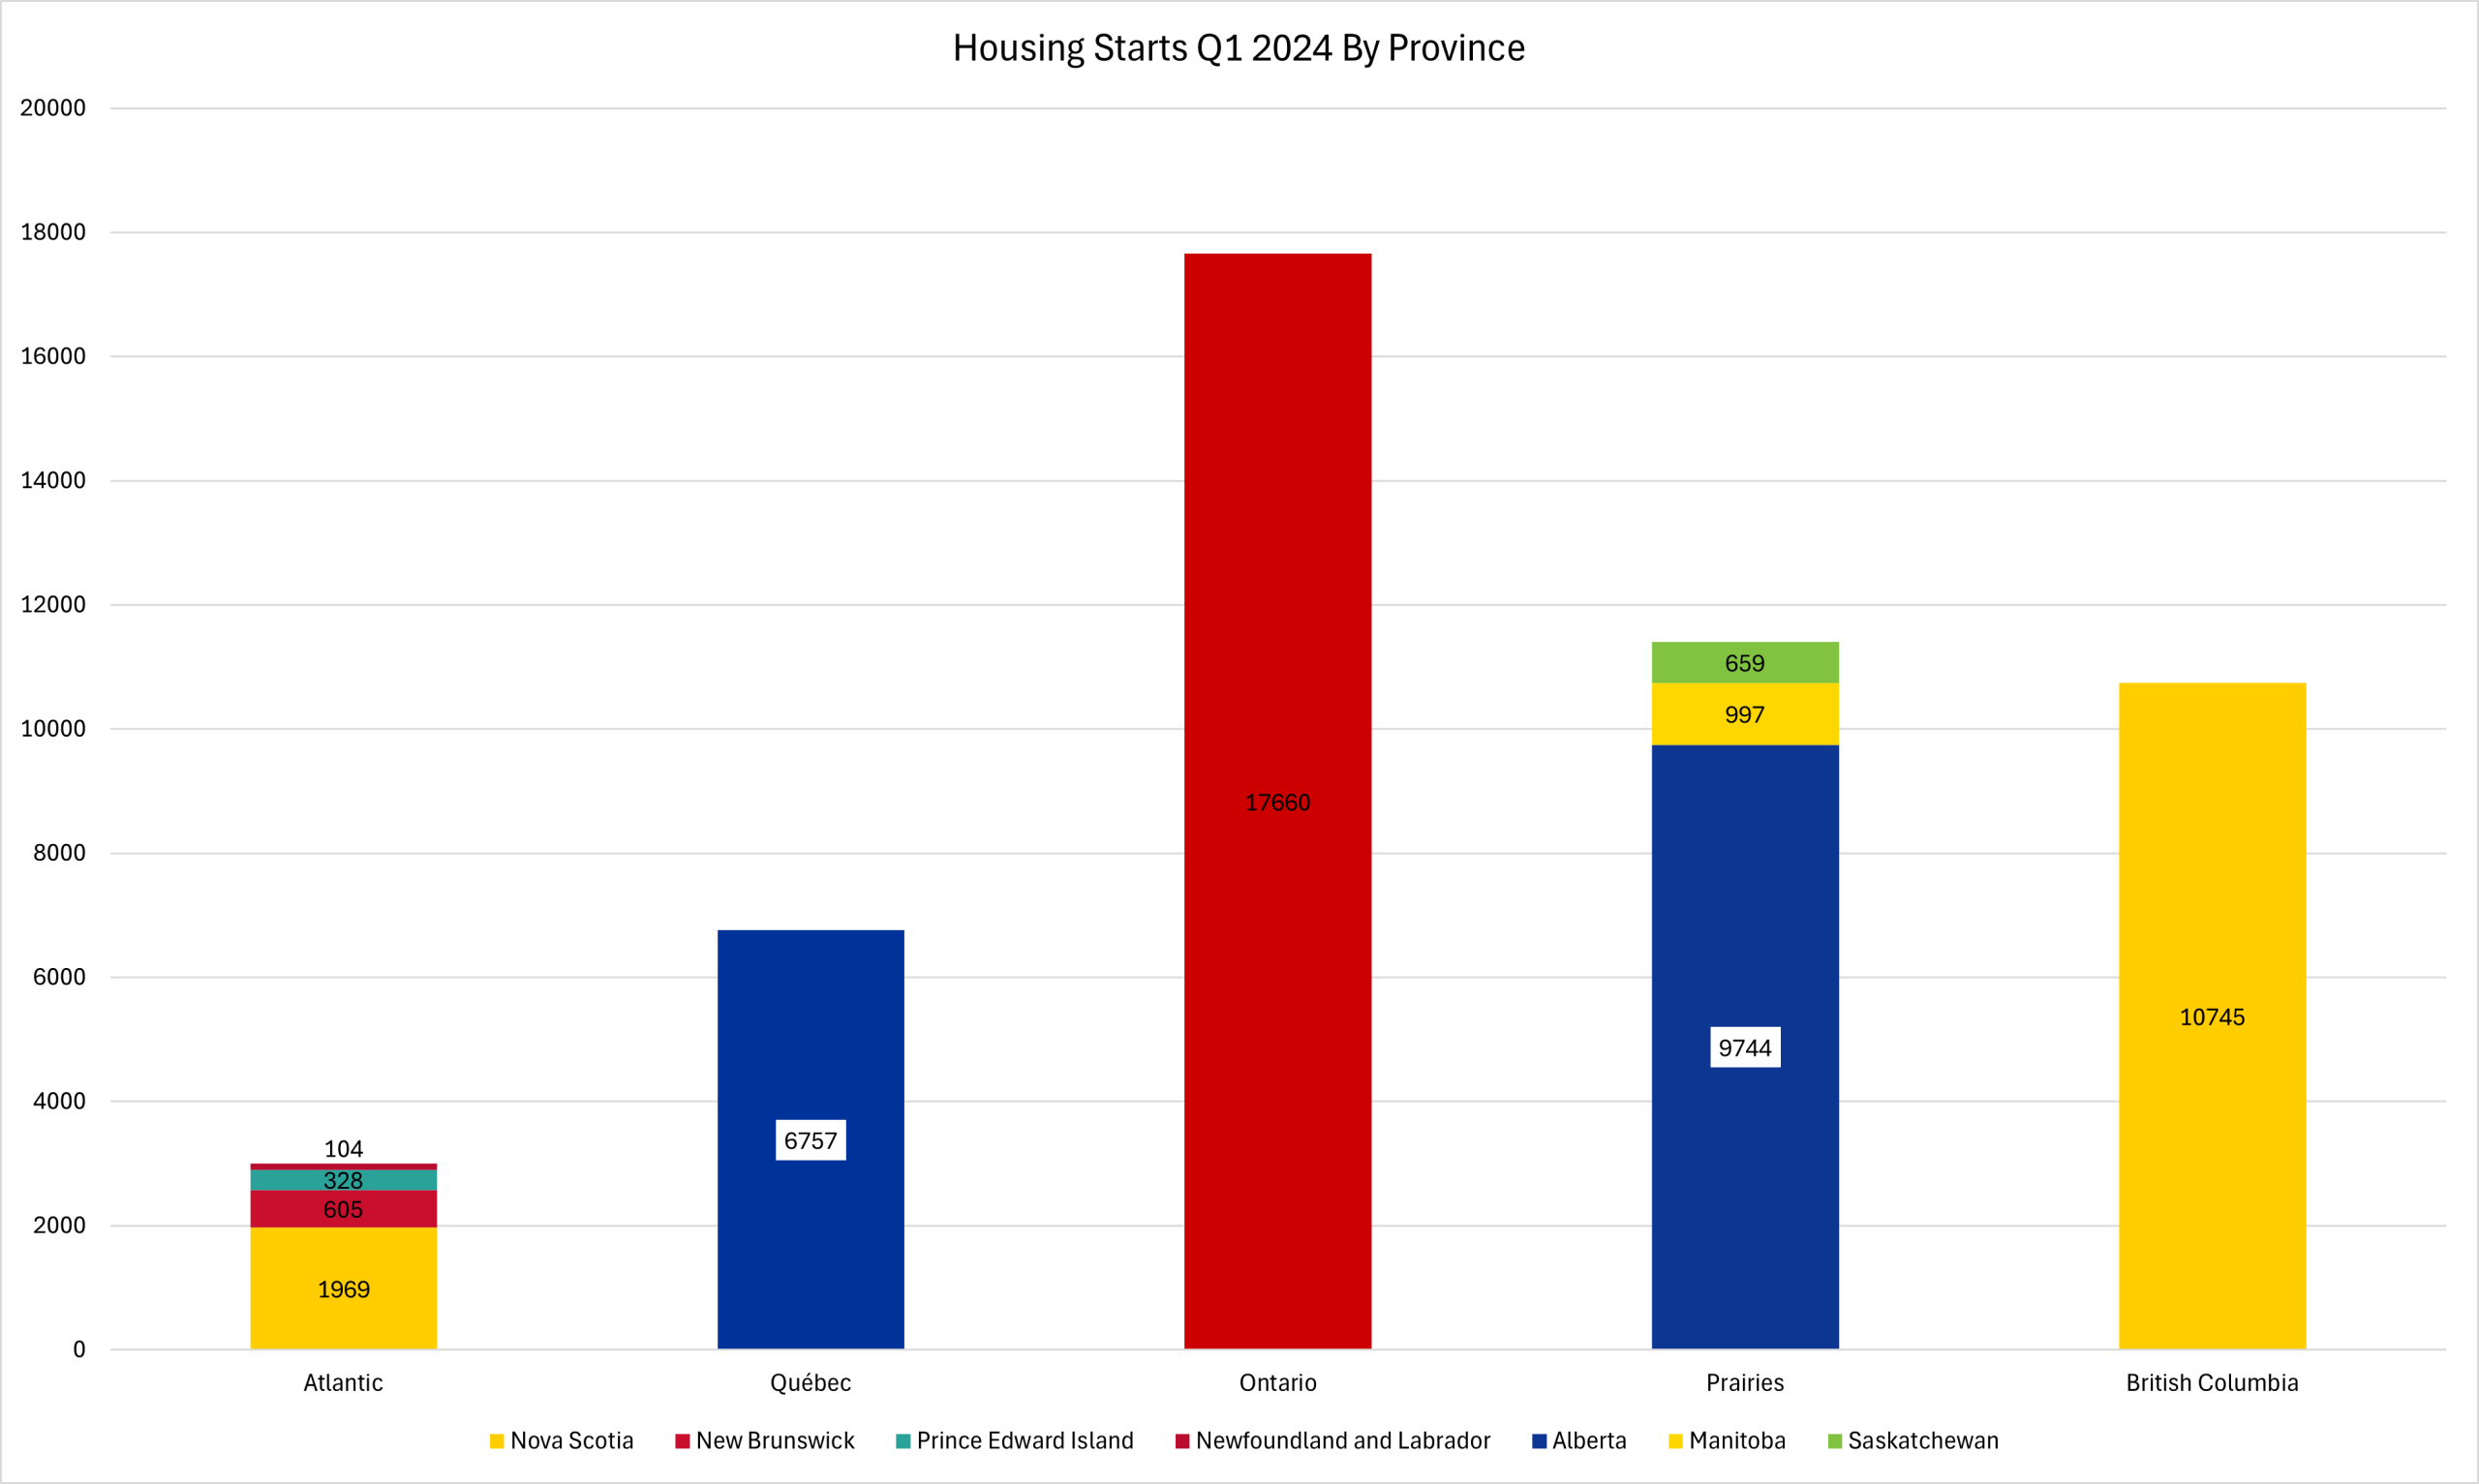
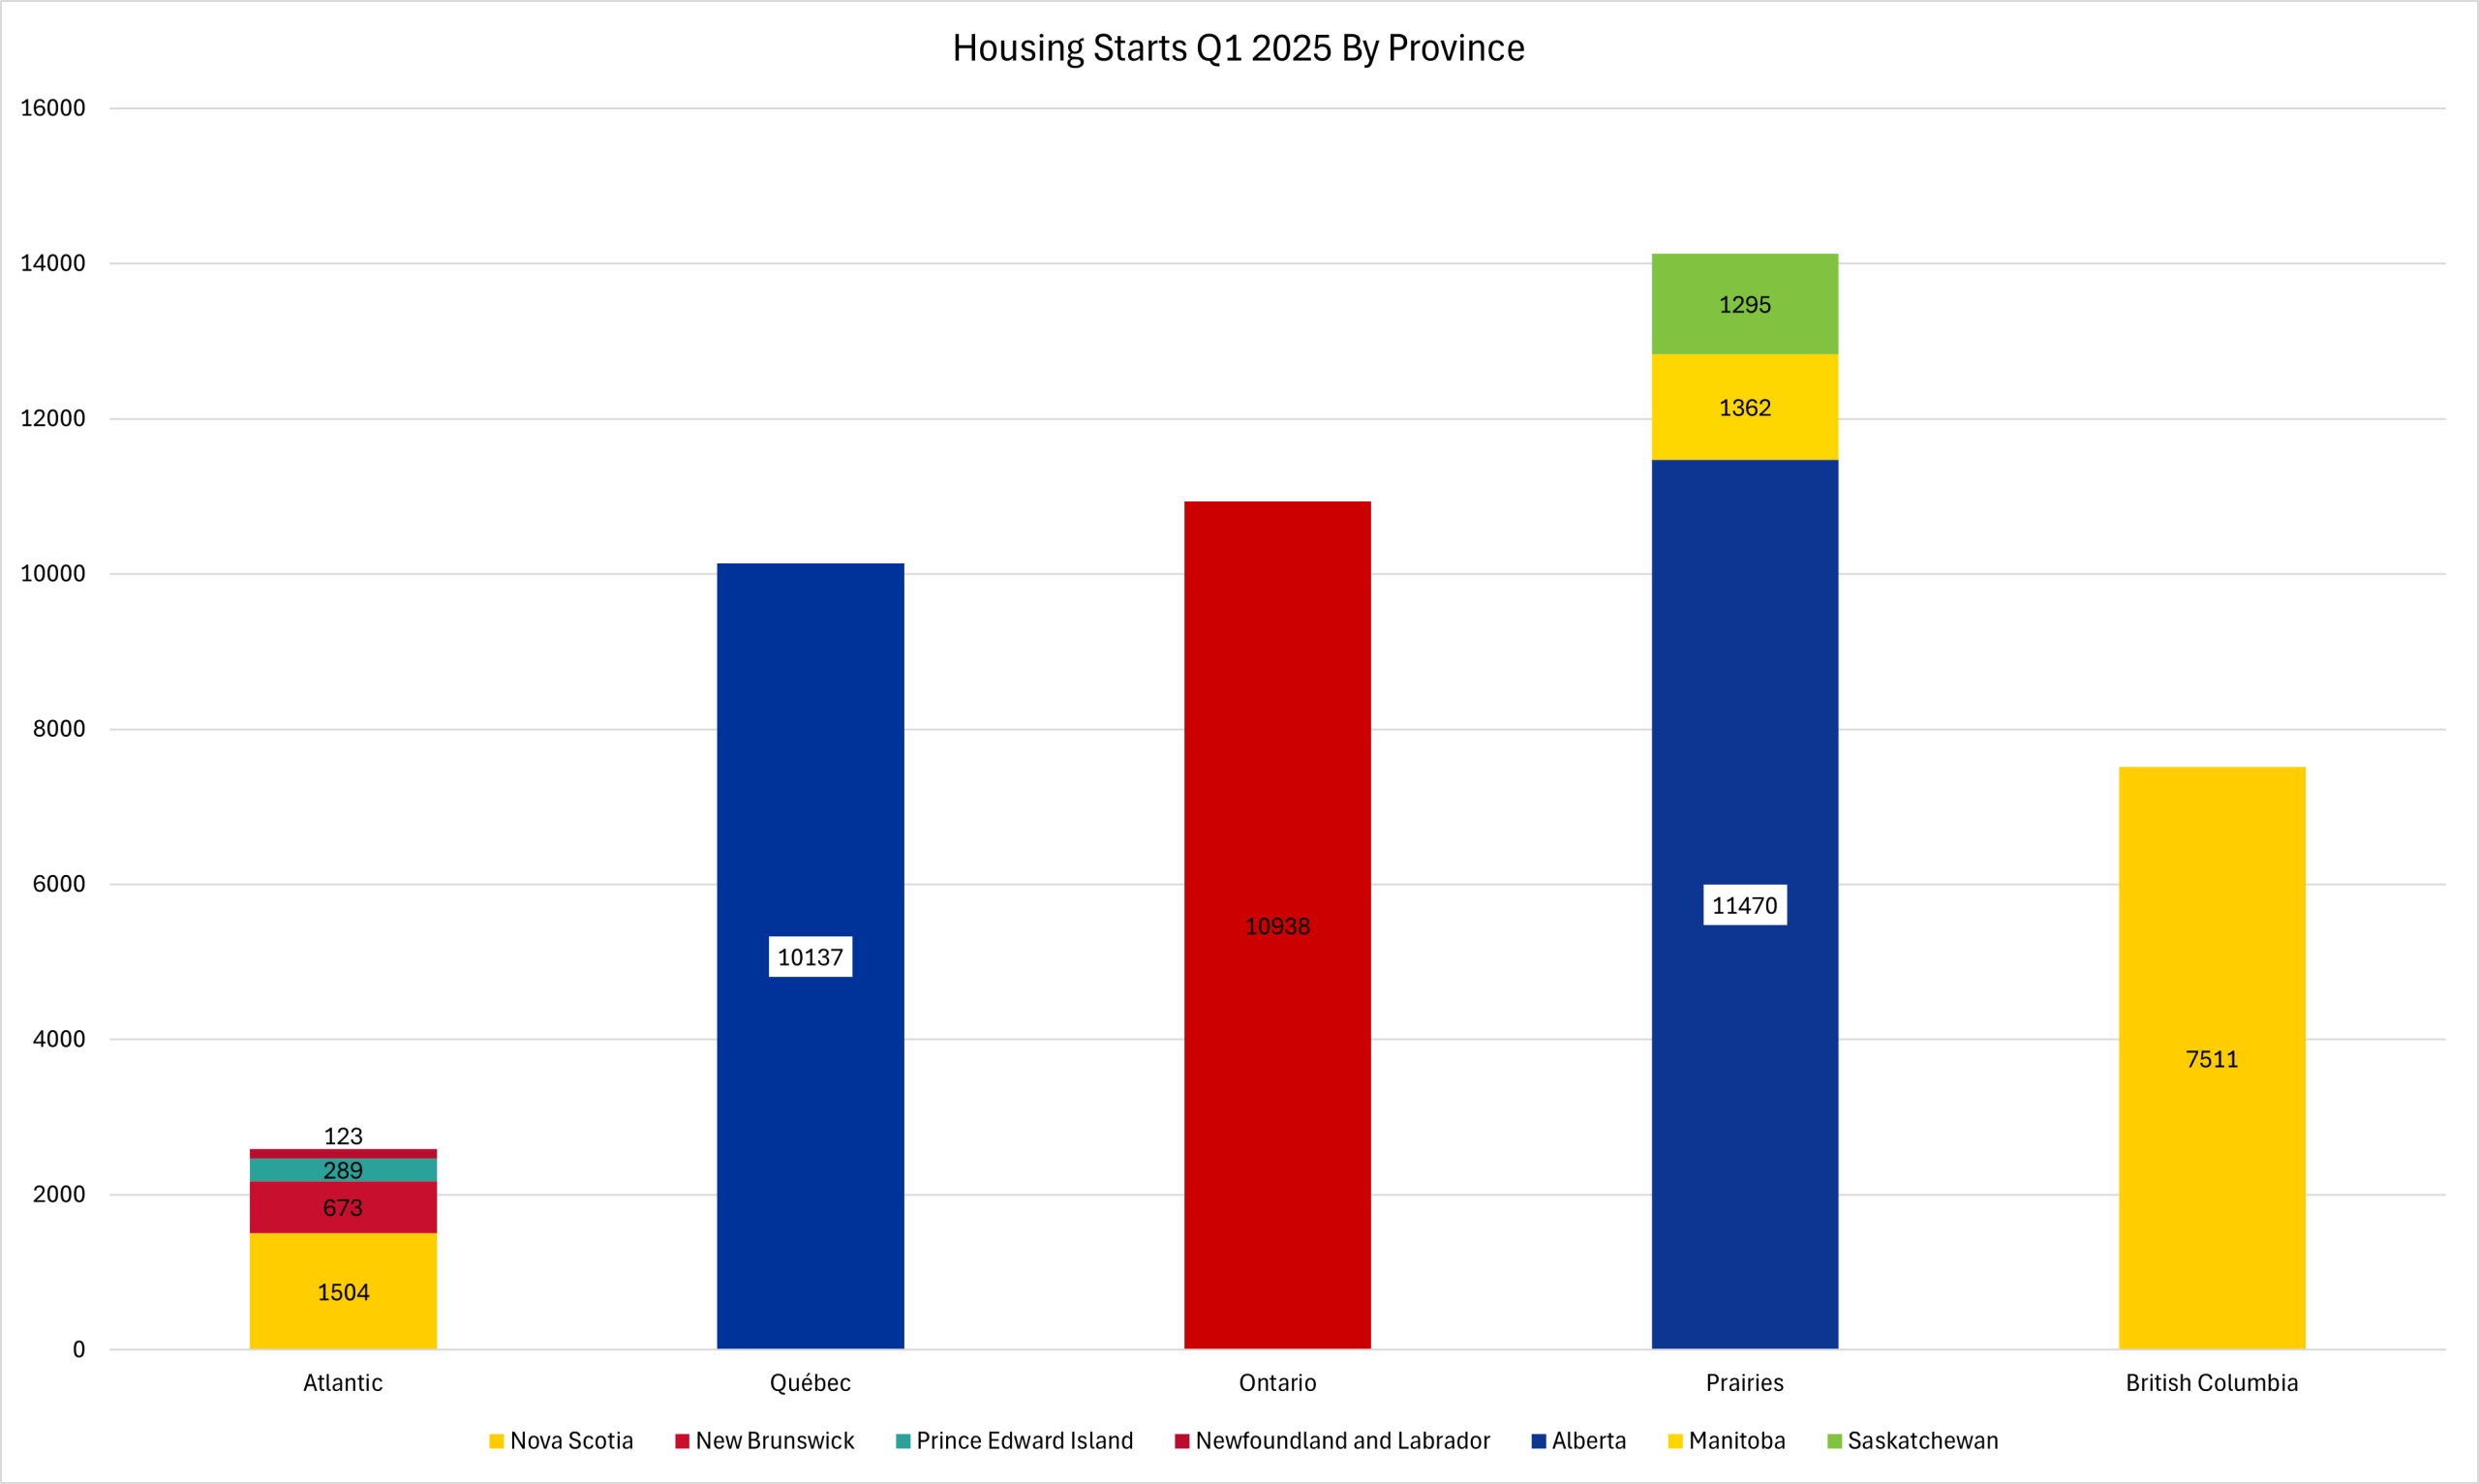
( Editor’s note: If you are on desktop, you can click these graphs to get a better look at them. )
Provincial Overview – Diverging Trends
Figure 1 and 2 summarizes Q1 2025 compared with Q1 2024. Saskatchewan nearly doubled its starts (+97 percent), while Quebec (+50 percent) and Alberta (+18 percent) registered notable gains. Ontario (–38 percent) and British Columbia (–30 percent) saw fewer projects break ground, though each remains a large share of national demand.
The Canadian Home Builders’ Association observes, “Ontario starts declined 38 percent year‑over‑year, reflecting both financing challenges and the timing of project approvals.” The same report stresses that activity levels remain above pre‑pandemic norms in many medium‑sized markets.
Rather than signalling defeat, slowdowns in large provinces indicate a market rebalancing after recent peaks, while growth elsewhere points to new opportunities for housing supply and wood‑product demand.
The Prairie Uplift
Alberta: Sustained Expansion
With 11,470 starts in Q1, Alberta accounted for roughly one‑quarter of all Canadian housing starts this quarter. Purpose‑built rental complexes in Calgary and Edmonton—a segment relying heavily on engineered wood floor systems and factory‑finished millwork—led the way.
Alberta’s Minister of Seniors, Community and Social Services called the numbers “evidence that policy changes to streamline approvals are translating into shovels in the ground.”
Saskatchewan: Rapid Acceleration
Saskatchewan’s 1,295 starts nearly doubled last year’s tally. Many six‑storey wood‑frame apartment blocks—enabled by the National Building Code’s mid‑rise provisions—are driving that growth in Saskatoon and Regina. Suppliers of laminated beams, pre‑hung doors, and modular kitchens are seeing lead‑time compression as developers race to meet rental demand.
Manitoba: Steady Climb
Manitoba added 1,362 starts (+38 percent), continuing a three‑year upward trend. Winnipeg remains the hub, with single‑detached and townhouse projects providing consistent demand for custom cabinetry and trim packages.
Prairie provinces collectively produced 24 percent of national starts, up from 17 percent a year ago—an important signal for manufacturers considering distribution hubs west of the Great Lakes.
Quebec’s Rental‑Driven Growth
Quebec logged 10,137 starts, a 50 percent year‑over‑year increase that underscores the province’s focus on rental supply.
The Association des professionnels de la construction et de l’habitation du Québec (APCHQ) notes, “Eighty percent of new units in Q1 were purpose‑built rentals, reflecting both demographic demand and tax incentives.”
Montreal, in particular, saw a 138 percent jump in March starts, bringing new opportunities for millwork shops specialising in multi‑unit interiors. With provincial and municipal programs expediting permitting for affordable rentals, Quebec’s market appears poised for sustained, if moderating, growth through 2025.
Slower Starts in Ontario and British Columbia
Ontario: Adjusting After a Strong Cycle
Actual starts in Ontario fell to 10,938, the lowest first‑quarter total since 2018. While striking, the decline follows an elevated multi‑year run. Developers cite high interest rates, labour‑cost pressures, and a recalibration of condo pre‑sales.
Economist Mike Moffatt notes, “The pause is partly cyclical. Once borrowing costs ease and existing inventory absorbs, many of these shelved projects are likely to re‑activate.”
Manufacturers should therefore treat Ontario’s pullback as a temporary reprieve rather than a permanent contraction.
British Columbia: Moderated Activity
British Columbia registered 7,511 starts (–30 percent), with Vancouver accounting for much of the decline. Builders report that financing for large towers tightened in late‑2024; several phased developments opted to push groundbreaking into the second half of 2025. Smaller interior markets such as Kelowna and Kamloops, however, continue to launch wood‑frame townhome clusters.
Ontario and B.C. still represented roughly 40 percent of national starts despite the quarterly slowdown. Their medium‑term outlook hinges on the pace of interest‑rate adjustments and municipal planning reforms.
Atlantic Canada – Mixed but Meaningful
- Newfoundland and Labrador initiated 123 starts (+18 percent)—small in absolute terms yet indicative of a stable recovery in St. John’s infill construction.
- New Brunswick added 673 starts (+11 percent), buoyed by Moncton’s expanding rental pipeline.
- Prince Edward Island recorded 289 starts (–12 percent), largely reflecting project timing rather than waning demand.
- Nova Scotia saw 1,504 starts (–24 percent) after two robust years; Halifax developers cite higher financing costs and construction‑trades capacity constraints.
For wood‑product suppliers, Atlantic demand may be uneven quarter‑to‑quarter, but the region’s multi‑unit emphasis keeps a dependable baseline.
 SAAR Context and Project Pipeline
Looking at the six‑month rolling average (SAAR) from October 2024 to March 2025, national starts stood at 220,043 units—only 2 percent below the prior period. Single‑detached activity edged up 5 percent, while multi‑unit starts eased 4 percent. Importantly, completions declined 17 percent nationwide, suggesting that inventories will remain tight, especially in provinces with growing populations and robust rental demand.
Implications for Secondary Wood Manufacturing
- Re‑balancing Supply Chains – Firms may consider expanding Prairie and Quebec distribution while maintaining capacity for eventual rebounds in Ontario and B.C.
- Labour Allocation – Trades shortages are most acute in Calgary, Saskatoon, and Montreal; project timelines may stretch unless prefabricated solutions increase.
- Product Mix – Increased rental construction favours durable, high‑volume wood components, whereas slower condo segments may delay demand for premium custom millwork.
- Logistics Planning – Westward freight costs are rising; wholesale manufacturers are consolidating shipments or exploring rail to contain expenses.
Policy Landscape and Market Outlook
Federal targets call for 580,000 annual housing starts to close the affordability gap—a target the current SAAR undershoots. Provinces are tackling the challenge differently:
- Alberta is expanding secondary‑suite allowances.
- Quebec offers tax credits for affordable rentals.
- Ontario is reviewing development‑charge structures to reignite condo pipelines.
- Federal regulators are signaling cautious rate cuts, which may restore financing confidence by late‑2025.
Manufacturers should track policy changes closely: a modest reduction in borrowing costs can rapidly reopen paused projects, particularly in big‑ticket condo markets.
A Nuanced Growth Picture
Canada’s housing‑starts landscape in Q1 2025 resists simple binaries. Urban giants paused, giving mid‑sized provinces and Prairie newcomers room to expand. For secondary wood manufacturers, the message is clear: opportunity exists across the spectrum—from large rental complexes in Montreal and Calgary to steady low‑rise builds in Manitoba and New Brunswick. By calibrating production lines and logistics to this evolving mosaic, the industry can support—and benefit from—the next wave of Canadian homebuilding.
Additional Graphs, A bigger picture:
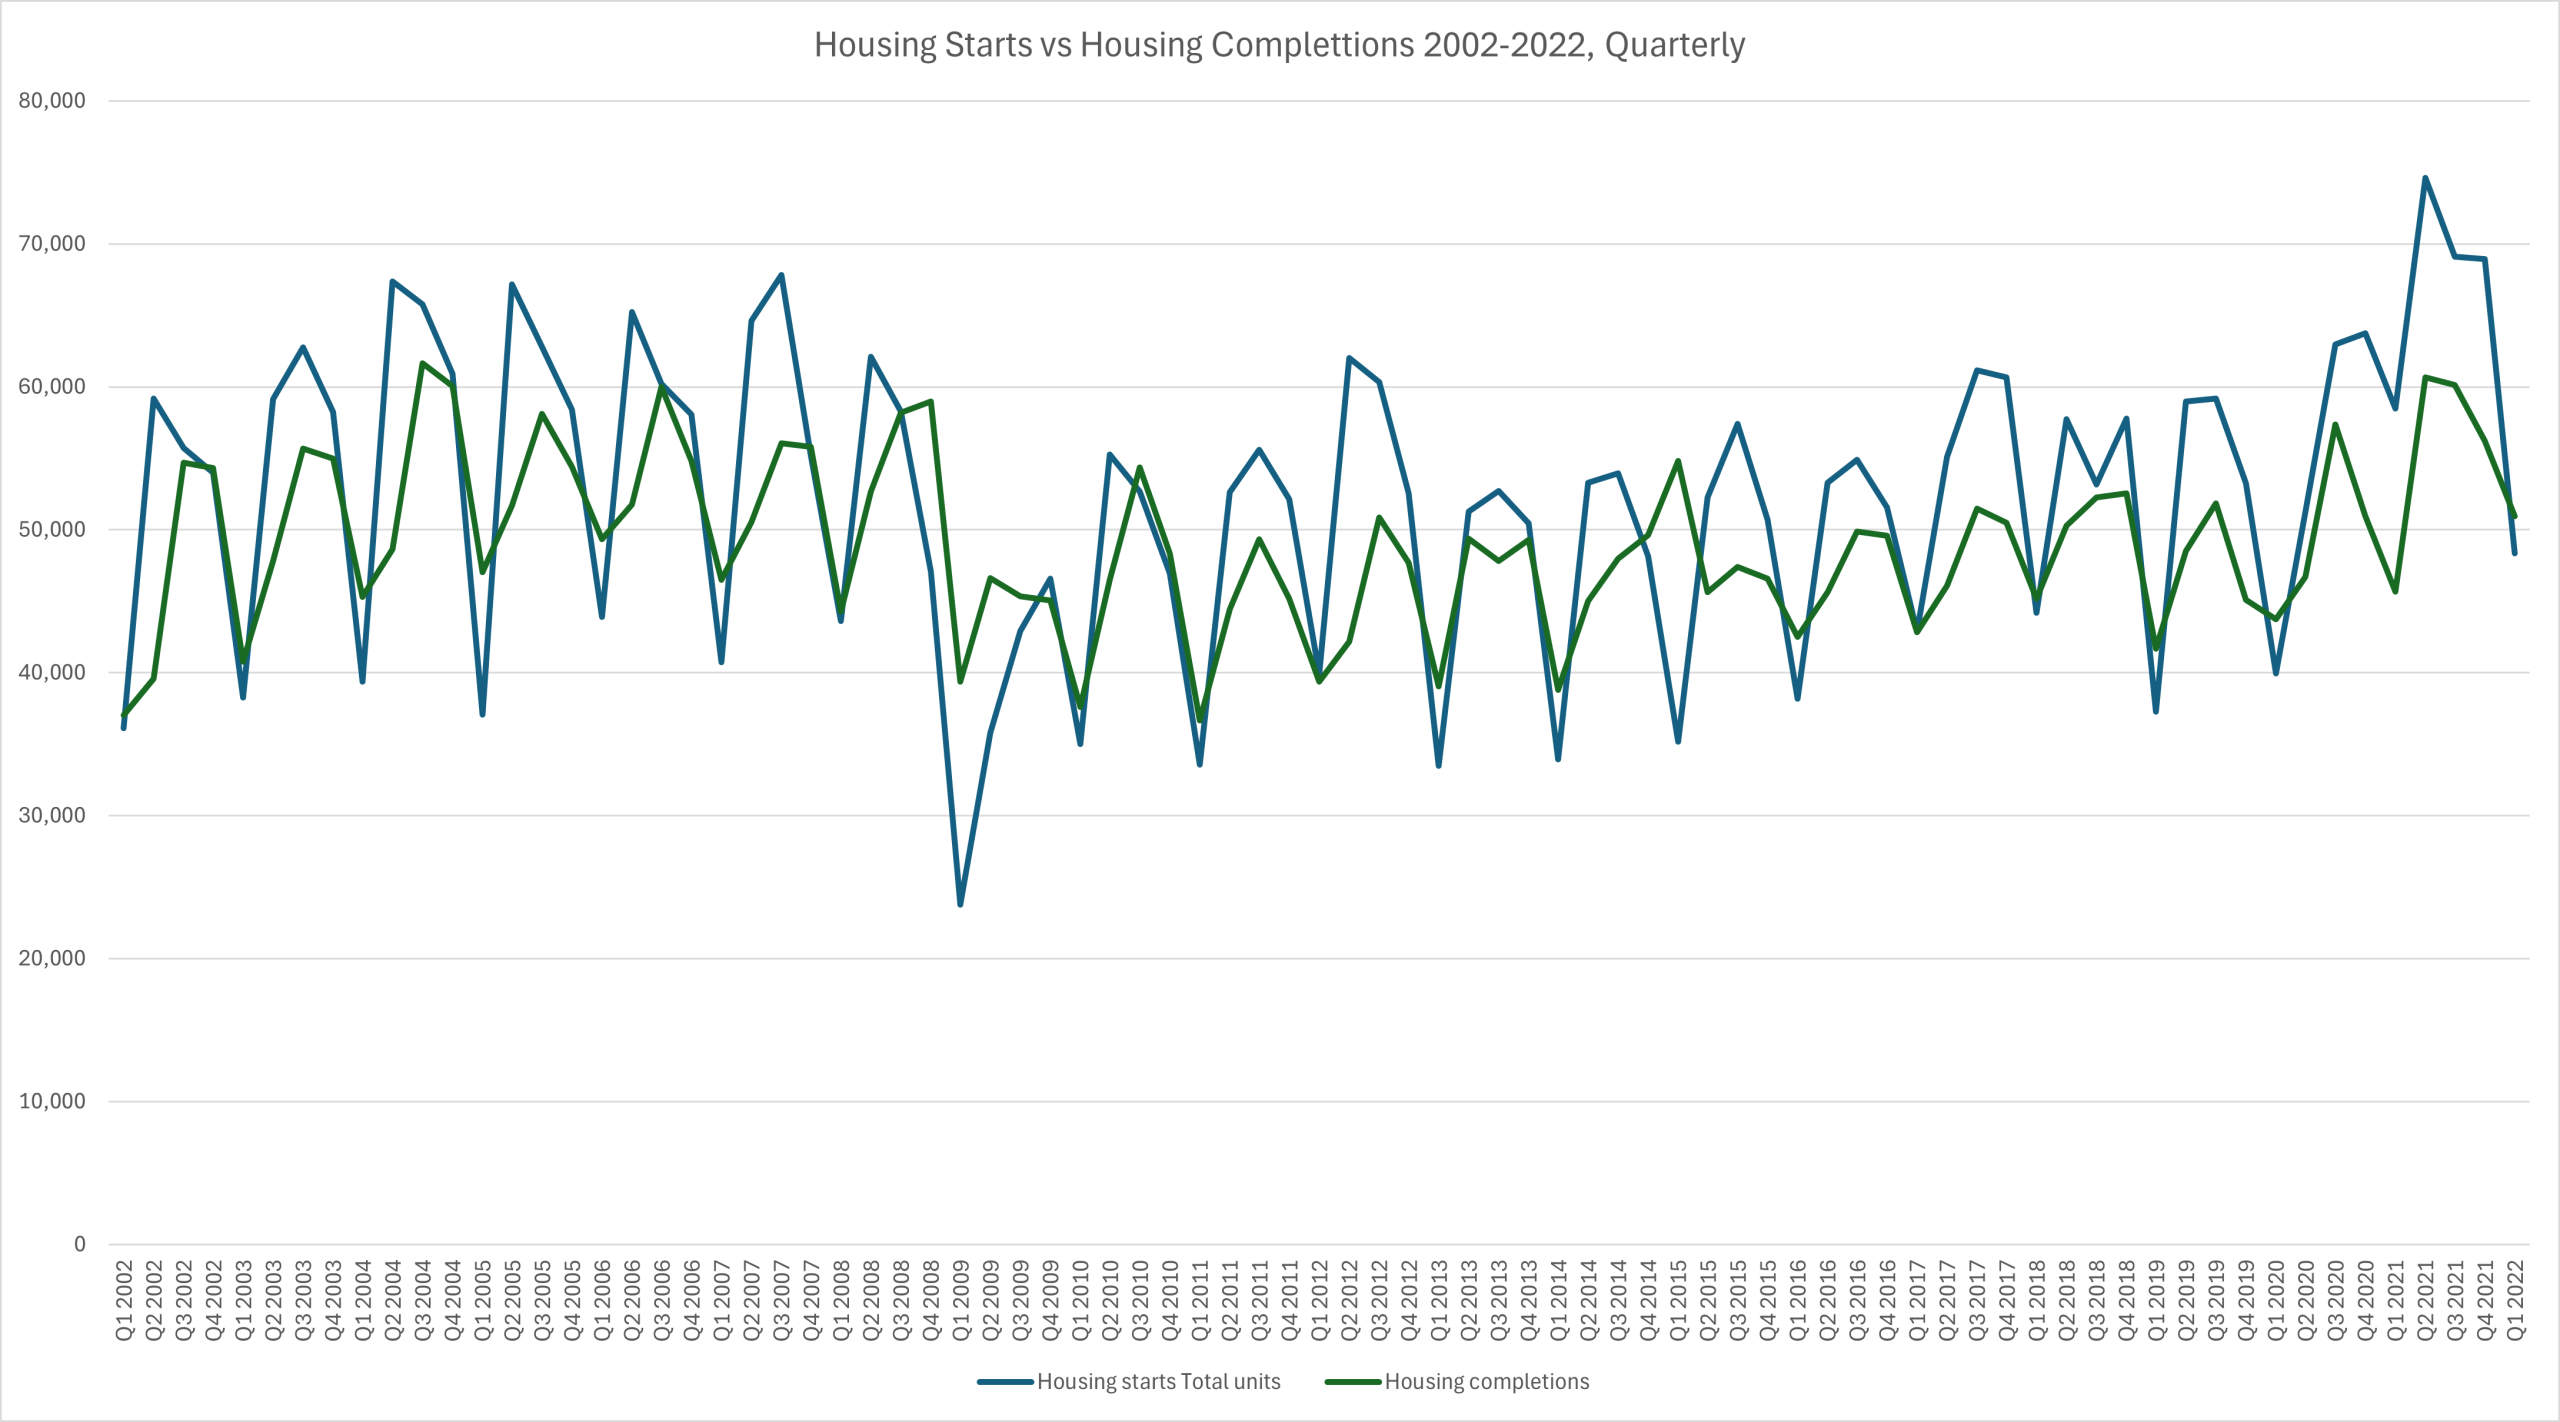
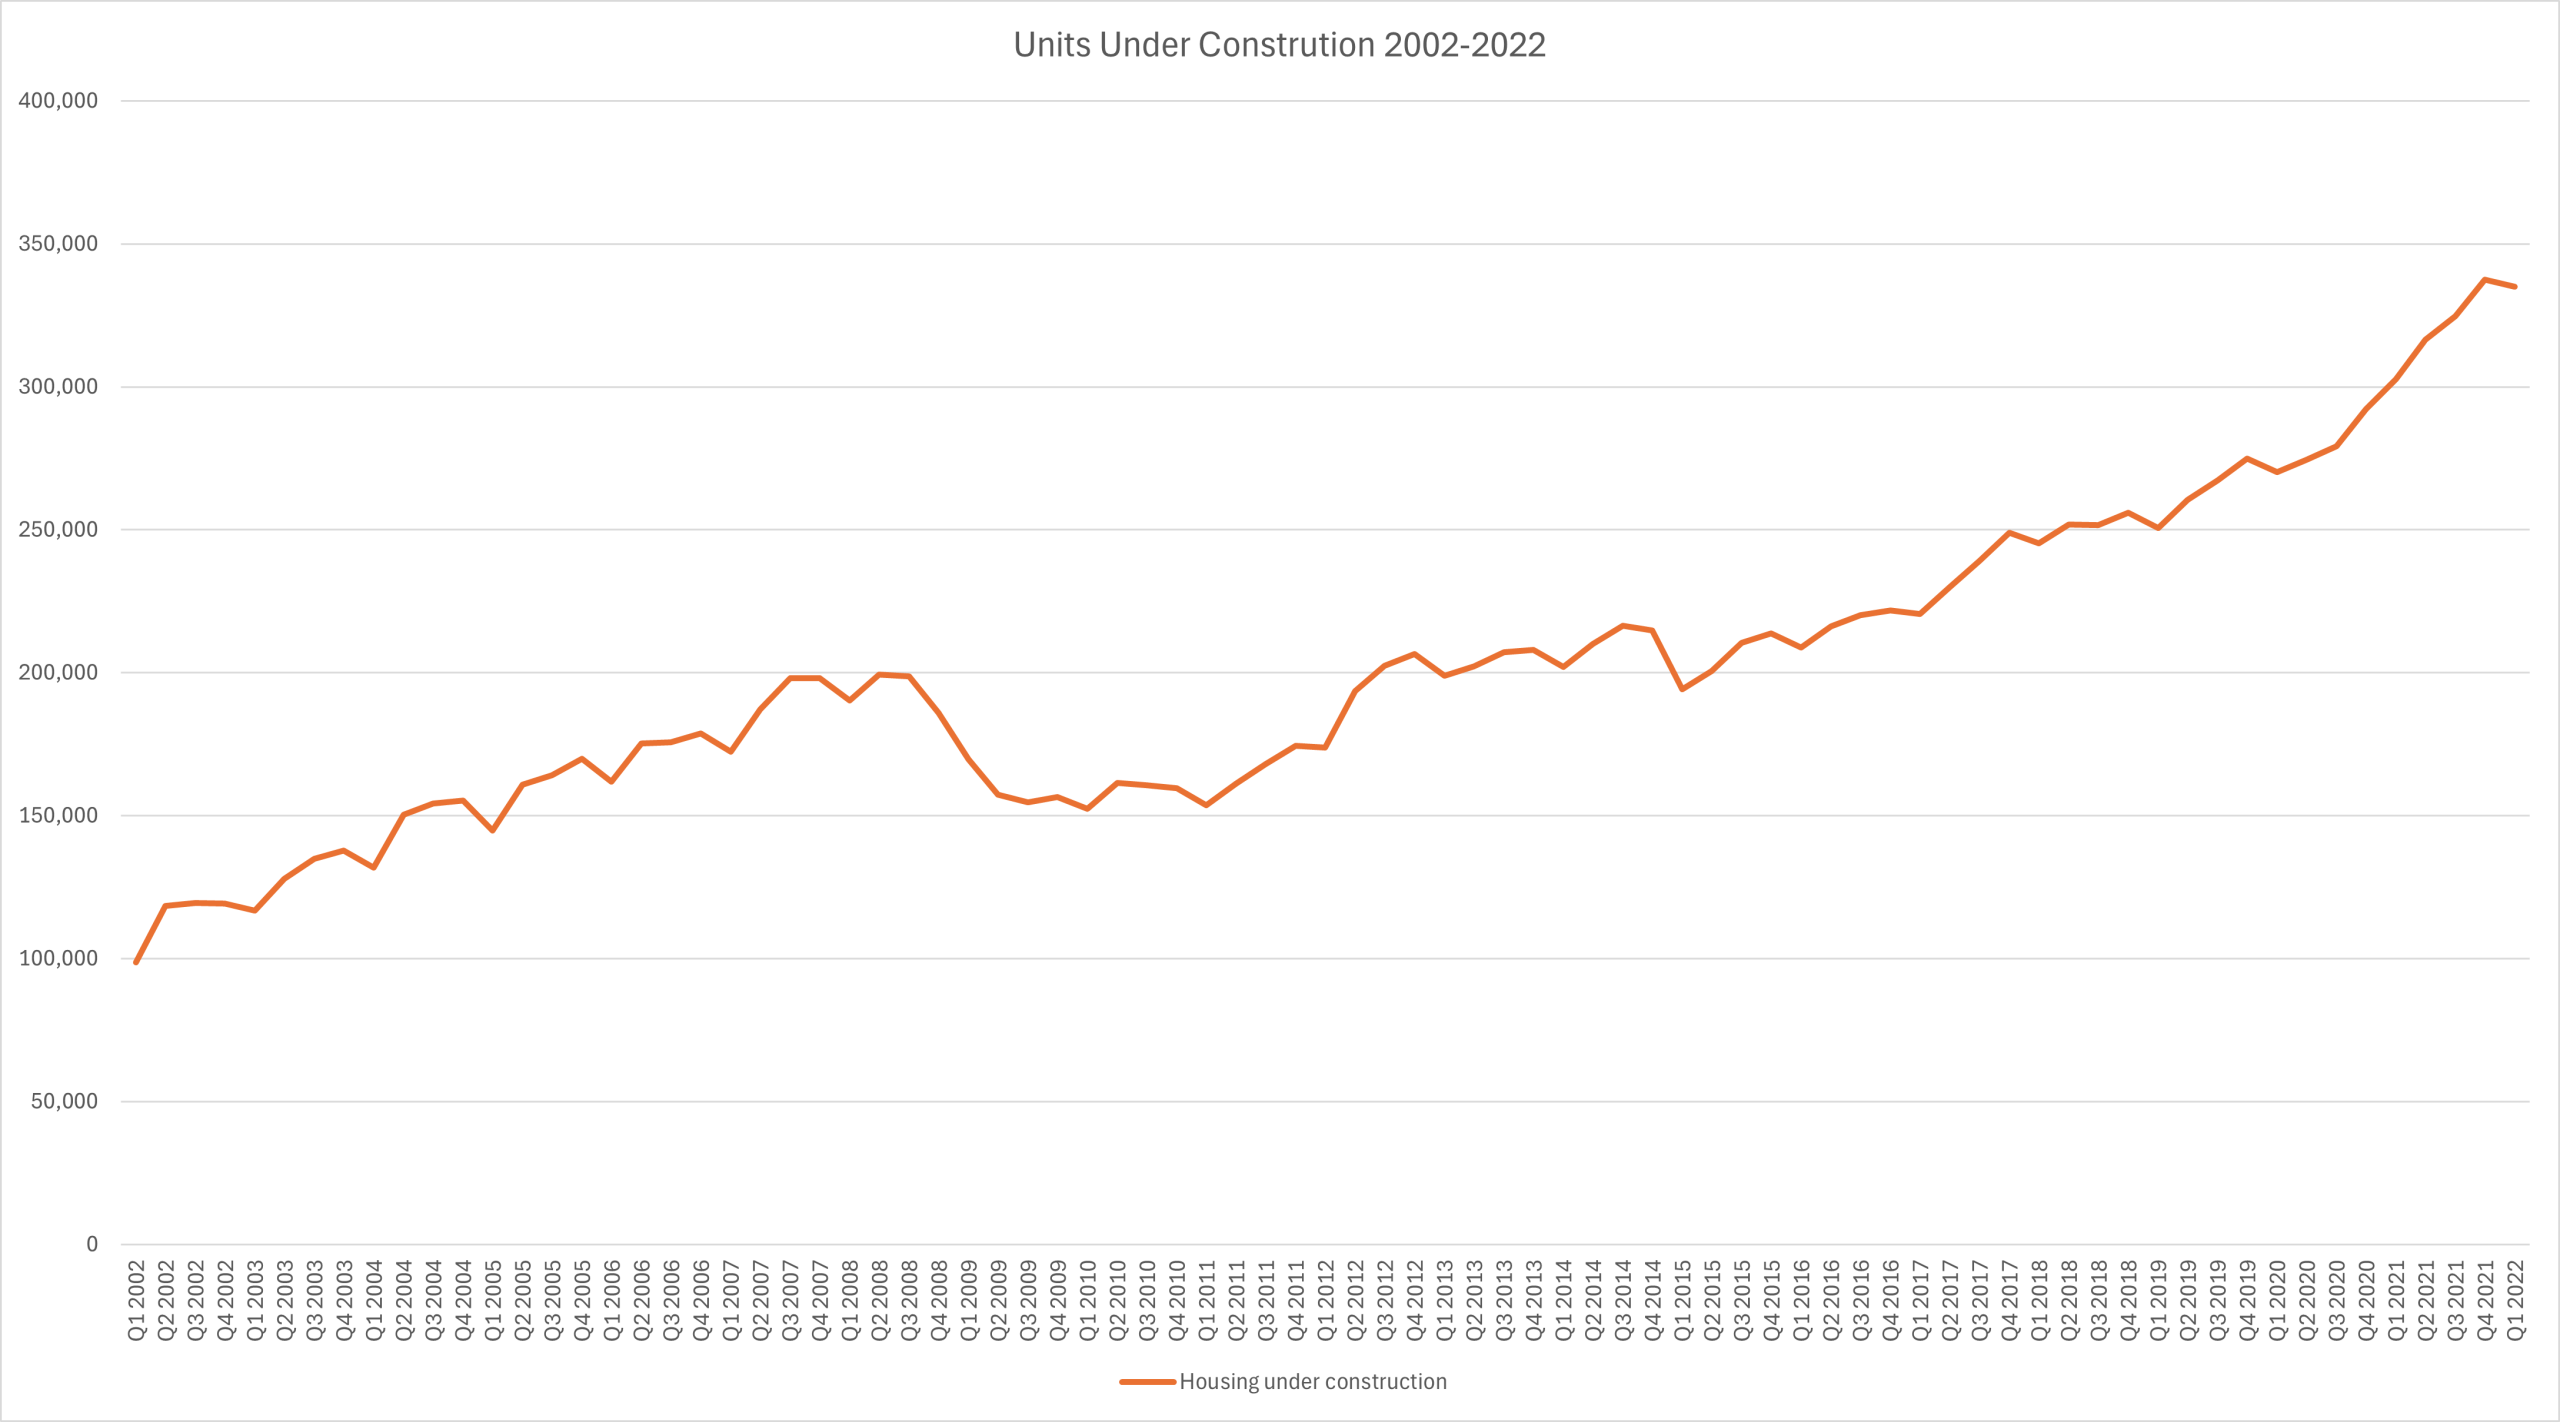
These last two graphs give the previous information more context. You can see that while housing starts have been growing, housing completions lag considerably behind, which has led to a massive backlog of approximately 350,000 units.
 Tyler Holt is the Editor of Wood Industry / Le monde du bois magazine. He has a master’s degree in literature and publication, and years of experience in the publishing and digital media industry. His main area of study is the effect of digital technologies on industrial and networked production.